What markets do
Rama Cont · 2001
Empirical properties of asset returns: stylized facts and statistical issues. A foundation for understanding heavy tails, volatility clustering and asymmetry.
Original quantitative research
A quiet afternoon and a market shock occupy the same calendar. They live in very different financial time. Our research turns that distinction into new mathematics for derivatives pricing and risk.
The problem worth solving
A model can match today's option prices and still tell the wrong story about tomorrow's risk. For a barrier, an autocall or an early-exercise decision, the journey matters as much as the destination.
Decades of empirical research document heavy tails, clustered volatility and asymmetric relationships between returns and risk. More recent work identifies remarkably irregular volatility at short horizons, alongside persistent behaviour over longer ones. Cont, Gatheral, Jaisson and Rosenbaum, and Bennedsen, Lunde and Pakkanen provide key landmarks.
Our starting point is to engineer these observations into the dynamics themselves. Calibration then tests a model built for the behaviour it is meant to explain.
The clock behind the clock
Calendar time counts minutes. A variance clock counts accumulated uncertainty: it moves slowly in calm conditions and quickly when risk intensifies. A volatility clock describes the pace at which volatility itself changes. These need not march together.
Financial clocks have a distinguished history, from Mandelbrot and Taylor and Clark to Ané and Geman and Geman, Madan and Yor. Our contribution develops this perspective into original analytical constructions and a working numerical framework.
The ambition is a practical financial time machine: explore possible market paths, revalue contingent obligations and understand how risk changes along the way.
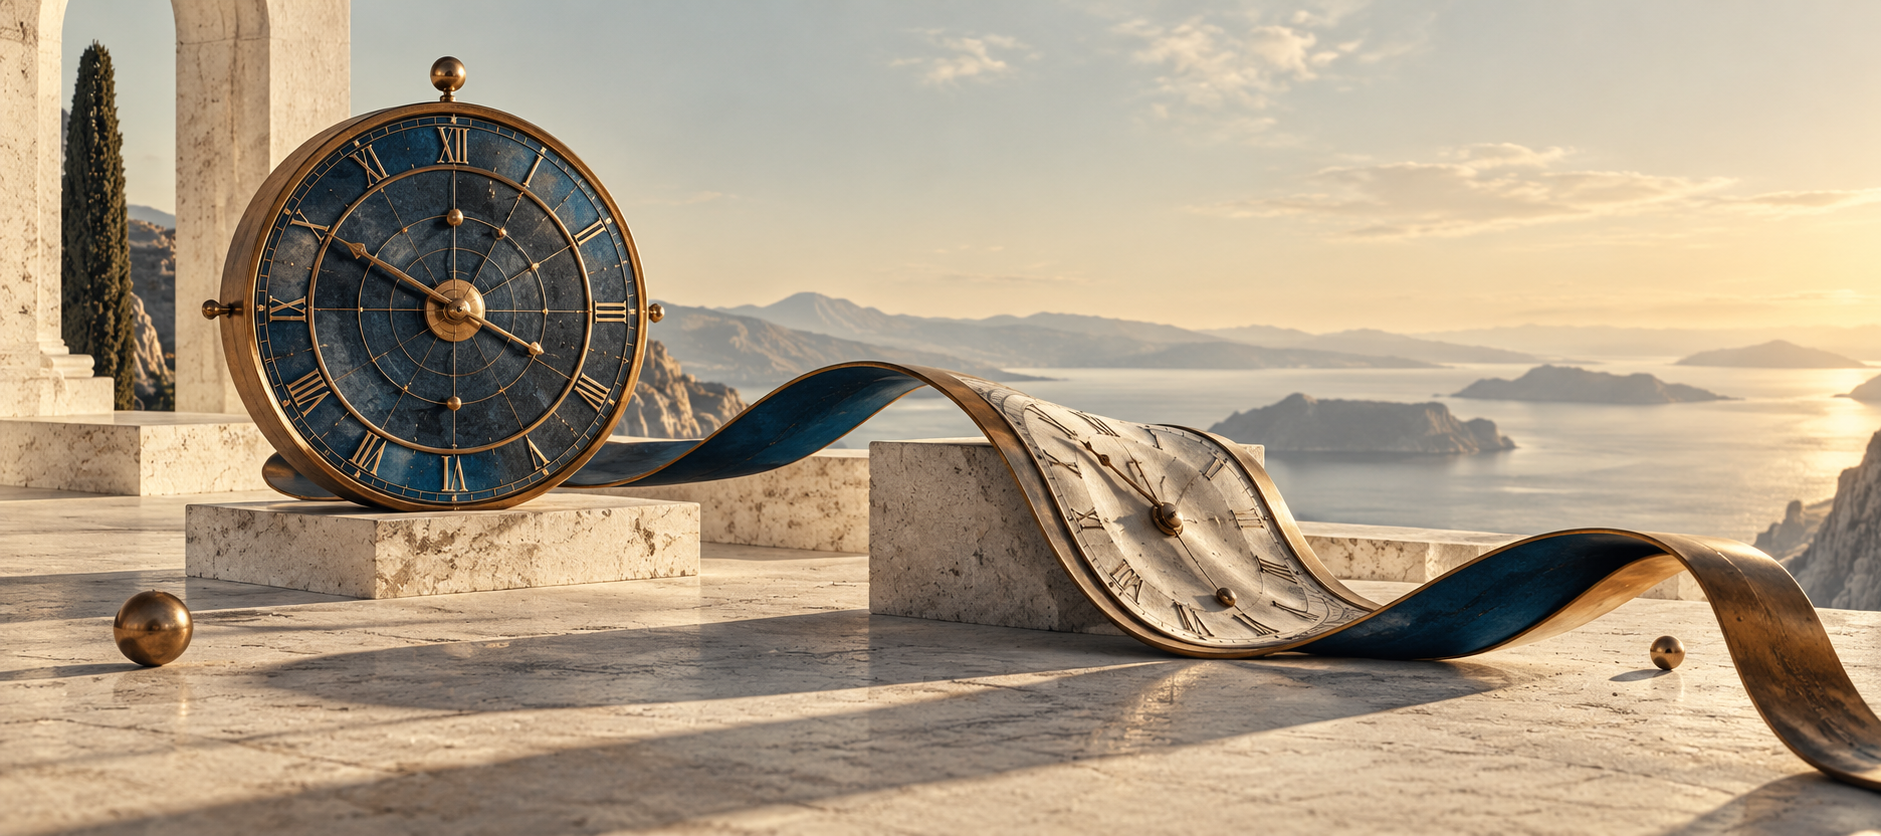
A visual echo of Dalí's The Persistence of Memory and a literary nod to Wells's The Time Machine. Here, the journey through time is mathematical.
Bespoke solutions to a universal pricing problem
Short-horizon roughness, longer-horizon persistence and return–volatility dependence guide the design. The aim is to connect the smile seen in option prices with a coherent account of how risk evolves.
Original analytical solutions, bespoke numerical methods and GPU computation are developed together. The working engine already supports SPX option calibration and pricing; numerical checks and later-date surface studies are part of the research programme.
A flexible payoff framework represents contingent cashflows, including basket autocalls and memory coupons. Research also includes Monte Carlo valuation for selected products with exercise rights.
From research to practice
The product vision connects a financial professional's existing AI application to product definition, calibration, valuation and hedge construction. The client's data and computing resources remain central to that workflow.
The mathematical engine is the foundation. AI provides a natural way to reach it. The integrated workflow is in development; today's public MCP gives AI clients access to the published research and SHTAR documents.
Explore the public research interfaceResearch trail
A selected reading list, from empirical observations to financial clocks and modern volatility models. These sources establish the context for our work.
What markets do
Empirical properties of asset returns: stylized facts and statistical issues. A foundation for understanding heavy tails, volatility clustering and asymmetry.
Financial time
On the Distribution of Stock Price Differences. An early distinction between market activity and ordinary elapsed time.
Random clocks
A Subordinated Stochastic Process Model with Finite Variance for Speculative Prices. Price changes viewed through a random activity clock.
Empirical transaction time
Order Flow, Transaction Clock, and Normality of Asset Returns. Evidence that the clock used to observe returns matters.
Diffusions and jumps
Time Changes for Lévy Processes. A mathematical bridge between time changes and discontinuous market moves.
A model benchmark
A Closed-Form Solution for Options with Stochastic Volatility with Applications to Bond and Currency Options. An influential analytical model linking stochastic volatility, correlation and option prices.
Short-horizon irregularity
Volatility is rough. Empirical evidence motivating a new generation of volatility models.
Rough-volatility pricing
Pricing under rough volatility. Connects roughness with option smiles and their maturity dependence.
More than one horizon
Decoupling the Short- and Long-Term Behavior of Stochastic Volatility. Distinguishes local roughness from longer-term persistence.
Selected public work
Related research
SHTAR connects terms, state and payments with the capabilities of a valuation provider.